Discretionary Support provides emergency financial help to people in Northern Ireland who are facing an extreme, exceptional or crisis situation.
It is intended for circumstances where a person or their immediate family could face a significant risk to their health, safety or wellbeing without urgent financial assistance.
Support can be provided as either a non-repayable grant or an interest-free loan, depending on the applicant’s circumstances and ability to repay.
It may help with essential living costs, basic household items, certain travel expenses and rent in advance. Eligibility depends on factors including income, savings, household circumstances, existing government debt and the nature of the crisis.
What Can Discretionary Support Help Pay For?
Discretionary Support is designed to deal with urgent financial needs rather than ordinary ongoing household expenses.
The Finance Support Service assesses each application individually and determines whether the requested assistance is necessary because of a genuine crisis or exceptional situation.
Support may potentially be provided for:
- Short-Term Living Expenses Such As Food And Essential Daily Costs
- Buying, Repairing Or Replacing Basic Household Items
- Essential Household Appliances Such As A Cooker
- Certain Travel Expenses In Limited Circumstances
- Rent In Advance To An Eligible Private Landlord
- Essential Costs Needed To Protect Health, Safety Or Wellbeing
The amount and type of support offered will depend on the applicant’s circumstances. Receiving assistance is not automatic simply because someone has a low income.
Short-Term Living Expenses
People experiencing an immediate shortage of money may be considered for support with essential living expenses. This could include food and other basic necessities where the person cannot reasonably meet those costs from available income or savings.
Living-expense support is intended to cover an immediate period of financial difficulty rather than provide ongoing income.
The Finance Support Service may consider when the applicant is due to receive their next income payment and whether that payment will be enough to meet essential needs.
Applicants should clearly explain what caused the financial crisis, what money is currently available and why their normal income cannot cover the immediate costs.
Essential Household Items And White Goods
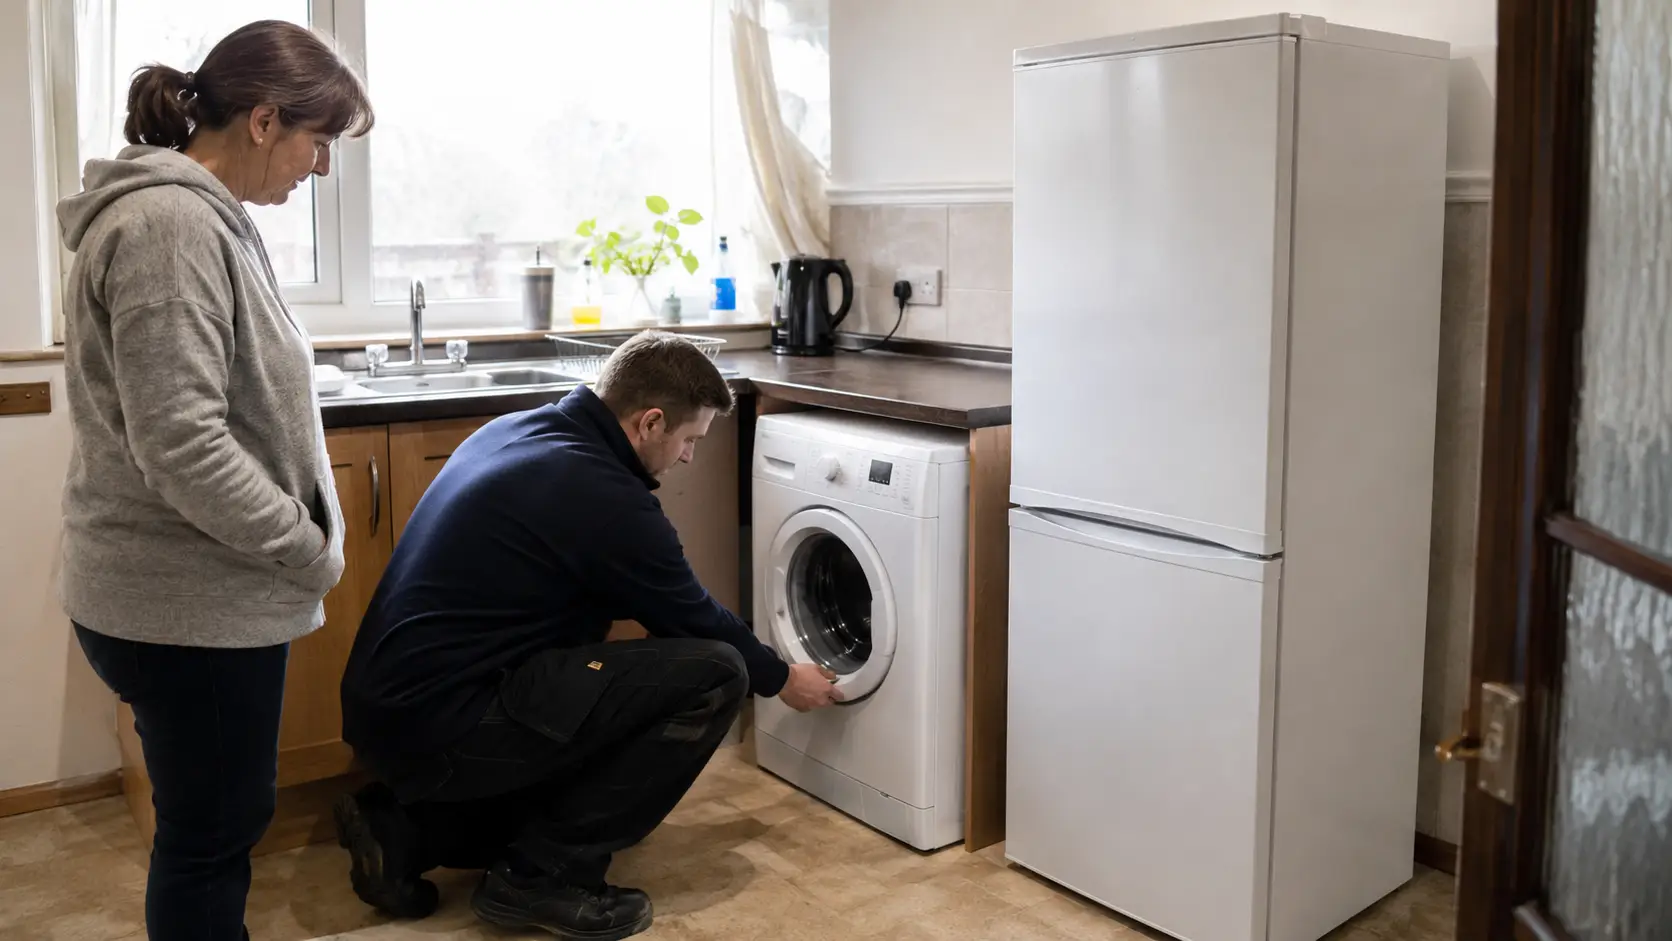
Discretionary Support may also help with buying, repairing or replacing basic household items where they are essential to everyday living.
A cooker is specifically recognised as an example of a basic household item. Washing machines are also referred to within the rules concerning repeat awards.
Other appliances may potentially be considered when they are genuinely essential, although approval depends on the individual assessment rather than a fixed list of eligible products.
The applicant should explain:
- What Item Is Needed
- Why The Item Is Essential
- Whether It Is Broken, Missing Or Unsafe
- Whether Children Or Vulnerable Household Members Are Affected
- How The Situation Creates A Risk To Health, Safety Or Wellbeing
- Why The Household Cannot Pay For The Item Without Assistance
Travel Costs And Rent In Advance
Limited travel costs may qualify where the journey is necessary because of the applicant’s crisis or exceptional circumstances.
Discretionary Support may also help with rent in advance in certain situations. This normally relates to rent paid to a landlord other than the Northern Ireland Housing Executive.
Applicants should provide clear details about why the accommodation is needed and why they cannot meet the advance payment from their own resources.
Who Is Eligible For Discretionary Support?
Eligibility is based on more than simply receiving benefits or having a low income. Applicants must demonstrate that they are facing an extreme, exceptional or crisis situation.
A person will normally need to:
- Live In Northern Ireland
- Have A Crisis That Arose In Northern Ireland
- Usually Be Aged 18 Or Over
- Be At Least 16 Where They Have No Parental Support
- Meet The Relevant Income Requirements
- Provide Details Of Available Savings
- Show That Health, Safety Or Wellbeing Is At Significant Risk
The Finance Support Service considers the applicant’s overall circumstances before making a decision.
Income And Savings Rules
Income is taken into account when assessing an application. The total annual income of the applicant and their partner, after relevant deductions, must normally remain within the applicable scheme limit.
Certain deductions and household expenses may affect how income is calculated. The Finance Support Service may also consider income that is excluded under the scheme rules.
Savings belonging to the applicant and their partner may also be considered. Having some savings does not necessarily mean an application will automatically fail, but available money can influence whether assistance is considered necessary.
Applicants should provide accurate information about:
- Wages
- Benefits
- Pension Income
- Other Regular Income
- Bank And Building Society Balances
- Savings
- Housing Costs
- Household Circumstances
Crisis Or Exceptional Circumstances
Discretionary Support is not designed to cover ordinary financial pressure or routine budgeting difficulties.
The situation must normally be serious enough to create a significant risk to the health, safety or wellbeing of the applicant or their immediate family.
Examples might include:
- Having No Safe Way To Prepare Food
- Losing Essential Household Items Following A Disaster
- Moving Into Accommodation Without Basic Household Items
- Experiencing A Sudden Loss Of Income
- Facing An Emergency Following Family Breakdown
- Leaving An Unsafe Home Situation
- Being Unable To Meet Immediate Essential Living Costs
- Needing Essential Equipment To Live Independently
Each case is assessed on its own circumstances, so similar applications may not always receive the same decision.
How Much Discretionary Support Can You Get?
There is no single standard payment that every successful applicant receives.
The amount offered depends on factors such as:
- The Nature Of The Crisis
- The Applicant’s Essential Needs
- Household Income
- Available Savings
- Existing Government Debt
- Previous Discretionary Support Awards
- The Cost Of The Essential Item Or Expense
- The Applicant’s Ability To Repay A Loan
If assistance is offered as a loan, the repayment amount must also be considered when deciding how much can reasonably be awarded.
The Finance Support Service may decide that a smaller amount than requested is sufficient to deal with the immediate crisis.
How Many Awards Can You Receive?
There are limits on how often some forms of Discretionary Support can be awarded.
Within a 12-month period, a person can normally receive up to three Discretionary Support loans for short-term living expenses and household items.
Different limits can apply to grants. Depending on the circumstances, someone may be able to receive:
- One Grant To Help Them Or Their Immediate Family Live Independently In The Community
- One Grant For Living Expenses In Qualifying Circumstances
These limits are important because previous awards can affect whether another application can be approved.
The 24-Month Rule For Household Items
A person who has already received Discretionary Support for a particular household item will normally be unable to receive another award for the same item within 24 months.
For example, a previous award for a washing machine could affect a new request for another washing machine during that period.
An exception may apply where the item has been lost or damaged because of a disaster.
Applicants should therefore provide accurate information about previous Discretionary Support awards when making a new claim.
Can Government Debt Affect Discretionary Support?
Government debt can have a significant effect on whether a Discretionary Support loan is available.
The Finance Support Service takes existing government debt into account when deciding whether an applicant can reasonably repay another loan.
Government debt can include amounts owed through:
- Previous Discretionary Support Loans
- Social Fund Loans
- Short-Term Benefit Advances
- Universal Credit Advances
An applicant and their partner who have total relevant government debt of £1,500 or more will normally be unable to receive another Discretionary Support loan.
This restriction relates specifically to loans. Grant eligibility is assessed separately according to the relevant circumstances and scheme rules.
Applicants should give complete and accurate information about existing government debts when applying.
How Do You Apply For Discretionary Support?
Applications can be made through the Finance Support Service.
People can normally apply online or contact the service by telephone where they cannot use the online application or require additional assistance.
Before applying, it is useful to prepare:
- National Insurance Number
- Details Of Income
- Benefit Information
- Rent Or Mortgage Costs
- Savings Information
- Bank Account Details
- Details Of Existing Government Debt
- Information About The Crisis
- Details Of Any Household Item Needed
Applicants should explain the circumstances clearly rather than simply stating that they need financial help.
What Evidence Do You Need?
The exact evidence required depends on the application.
Useful information may include:
- Proof Of Identity
- Proof Of Address
- Wage Slips
- Benefit Details
- Bank Statements
- Savings Information
- Rent Or Mortgage Details
- Evidence Showing The Crisis
- Information About A Broken Or Missing Household Item
- Supporting Information From A Housing Adviser Or Support Worker
Where an appliance is needed, explain why the item is essential and how living without it affects the household.
Providing complete information can help the Finance Support Service understand the situation and reduce the need to request additional details.
What Happens After You Apply?
After an online application is submitted, the applicant should normally wait for the Finance Support Service to contact them rather than making another application for the same need.
The service may ask for additional information before making a decision.
In some circumstances, an applicant may be asked to attend a Jobs and Benefits office to provide further information.
The outcome will depend on the evidence provided, the applicant’s circumstances and whether the situation meets the Discretionary Support rules.
Successful applicants will be told whether they have been awarded a grant or loan and the amount available.
How Is Discretionary Support Paid And Repaid?
A successful Discretionary Support award is normally paid into the bank, building society or credit union account provided during the application.
Applicants should make sure their payment details are correct.
A grant does not need to be repaid.
A Discretionary Support loan is interest-free but must be repaid.
Repayment arrangements depend on the applicant’s circumstances. Some repayments can be collected through deductions from qualifying benefits.
People receiving Universal Credit, or people who do not receive a benefit from which deductions can be taken, may need to repay through Direct Debit.
Applicants should understand before accepting a loan:
- The Total Amount Borrowed
- The Repayment Amount
- How Often Payments Will Be Collected
- How Repayments Will Affect Their Household Budget
Because the loan is interest-free, the borrower repays the amount owed without additional interest charges.
What If Your Discretionary Support Application Is Refused?
An application may be refused where the Finance Support Service decides that the circumstances do not meet the scheme requirements.
Possible factors may include:
- The Situation Does Not Meet The Crisis Threshold
- Health, Safety Or Wellbeing Is Not Considered At Significant Risk
- Residency Requirements Are Not Met
- Income Is Above The Relevant Limit
- Available Savings Mean Emergency Assistance Is Not Considered Necessary
- Award Limits Have Already Been Reached
- The Same Household Item Has Been Funded Within The Previous 24 Months
- Relevant Government Debt Prevents Another Loan
- Insufficient Information Has Been Provided
A refusal does not necessarily mean the applicant has no further options.
How To Request A Review?
An applicant who disagrees with the decision can ask the Finance Support Service to review it.
A review should normally be requested within 28 days of the decision.
When requesting a review, the applicant should explain:
- Why They Believe The Decision Is Incorrect
- Whether Important Evidence Was Overlooked
- Why The Item Or Expense Is Essential
- How The Situation Affects Health, Safety Or Wellbeing
- Whether Household Circumstances Have Changed
- Whether Children Or Vulnerable People Are Affected
If the applicant remains dissatisfied after the Finance Support review, they may be able to ask the independent Discretionary Support Commissioner to review the case.
The second review must also normally be requested within the relevant time limit.
What Other Financial Support Is Available?
Discretionary Support is only one form of emergency financial assistance.
The most appropriate option depends on the person’s benefit status, reason for needing money and whether the support will need to be repaid.
Universal Credit New Claims Grant
Someone who has recently made a new Universal Credit claim may be able to receive short-term support through the Universal Credit New Claims Grant where the relevant conditions are met.
This is different from a Universal Credit Advance and should not automatically be treated as the same form of support.
People experiencing financial difficulty after submitting a new Universal Credit claim should explain their circumstances to the Finance Support Service so the appropriate form of assistance can be considered.
Short-Term Benefit Advance
A Short-Term Benefit Advance may be available to someone waiting for their first payment after making a new claim for certain benefits other than Universal Credit.
It can provide temporary help where the claimant is experiencing financial need while waiting for the benefit payment.
Eligibility depends on the benefit being claimed and the applicant’s circumstances.
Budgeting Loan And Budgeting Advance
A Budgeting Loan can help eligible people receiving certain legacy benefits with essential costs such as furniture and household equipment.
It is interest-free but must be repaid.
People receiving Universal Credit cannot normally receive a Social Fund Budgeting Loan.
Universal Credit claimants may instead be able to apply for a Budgeting Advance if they meet the relevant requirements.
A Budgeting Advance is also repayable and should therefore be considered carefully alongside existing deductions and household expenses.
What Is Changing With Discretionary Support In 2026?
Northern Ireland’s Discretionary Support scheme continues to play a role in emergency financial assistance during 2026.
In September 2026, changes were announced concerning support for people facing difficulties with home heating costs.
The proposed changes are intended to broaden access to fuel-related assistance so that support is not restricted according to the type of home heating used.
Further implementation details are expected through official guidance.
Until revised rules formally take effect, applicants should continue to follow the existing Discretionary Support eligibility and application requirements.
Anyone applying for emergency assistance should provide up-to-date information about their circumstances so the Finance Support Service can determine which support option is available.
Is Discretionary Support Different Across The UK?
Discretionary Support is specifically a Northern Ireland scheme.
Similar emergency assistance exists elsewhere in the UK, but the scheme names, eligibility rules, payment limits and application processes are different.
Northern Ireland uses Discretionary Support.
Wales operates the Discretionary Assistance Fund, which includes different forms of emergency and individual assistance.
Scotland provides emergency help mainly through the Scottish Welfare Fund, including Crisis Grants and Community Care Grants.
England uses locally delivered crisis support arrangements, including funding through the Crisis and Resilience Fund.
Applicants should always apply through the scheme covering the nation where they live rather than assuming that Northern Ireland rules apply throughout the UK.
Conclusion
Discretionary Support can provide important emergency financial assistance to people in Northern Ireland facing an extreme, exceptional or crisis situation.
Help may cover essential living costs, basic household items, limited travel costs and rent in advance, depending on the circumstances.
Support may be provided as either a grant or an interest-free loan, and eligibility depends on income, savings, government debt, previous awards and the seriousness of the situation.
Applicants should provide complete evidence and clearly explain how the crisis affects their health, safety or wellbeing.
People who are refused support can request a review, while other Finance Support options may also be available when Discretionary Support is not appropriate.
FAQs
Can You Get Discretionary Support On Universal Credit?
Yes. Receiving Universal Credit does not automatically prevent someone from being considered for Discretionary Support. The Finance Support Service will still assess the crisis, household finances, savings, government debt and other relevant circumstances.
Can Discretionary Support Pay For White Goods?
Discretionary Support may help with essential household items where the need arises from an extreme, exceptional or crisis situation. A cooker is specifically recognised as an example, while washing machines are also referred to within the scheme rules.
Do You Have To Repay Discretionary Support?
It depends on the type of award. A grant does not need to be repaid. An interest-free Discretionary Support loan must be repaid according to the agreed repayment arrangement.
Can You Apply More Than Once?
Yes, but limits apply. A person can normally receive up to three qualifying Discretionary Support loans during a 12-month period. Separate limits also apply to grants and repeated awards for the same household item.
Can Savings Affect Your Application?
Yes. The applicant’s savings and their partner’s savings may be considered when deciding whether emergency support is required. Applicants should provide accurate details of all available funds.
Can Government Debt Stop You Getting Support?
Government debt can prevent someone from receiving another Discretionary Support loan. Where the applicant and their partner have relevant government debt totalling £1,500 or more, another loan will normally not be available.