The HMRC Personal Allowance increase campaign calls for the tax-free allowance to rise from £12,570 to £18,000. The proposal has not been approved, and there is no confirmed start date. It is a public petition, rather than an HMRC initiative.
For a basic-rate taxpayer using the full additional allowance, the proposal could mean an illustrative Income Tax saving of £1,086 a year. The actual benefit would depend on income, tax rules and any changes to benefits.
| Campaign Detail | Position When Checked on 11 September 2026 |
| Standard Personal Allowance | £12,570 |
| Proposed Personal Allowance | £18,000 |
| Petition signatures | 70,166 |
| Signatures needed to reach 100,000 | 29,834 |
| Petition closing date | 30 September 2026 |
| Approved implementation date | None |
Last Updated: 11.09.2026
What Is the HMRC Personal Allowance Increase Campaign?
Mike Haynes launched the official Parliament petition on 31 March 2026, asking for a £5,430 increase in the Personal Allowance.
Although the campaign is often associated with HMRC, it is a request for a change in government tax policy. HMRC administers the tax system but does not run this petition.
Latest Petition Signatures and Closing Date
The petition had passed 70,000 signatures when checked on 11 September. The total is a dated snapshot and may change before its September deadline.
Its growing support raises a practical question for households: how much difference would a higher allowance make to the tax they actually pay?
Why Are Campaigners Calling for an £18,000 Personal Allowance?
The central issue is the gap between rising incomes and a tax-free threshold that stays unchanged.
The Personal Allowance has stood at £12,570 since the 2021/22 tax year. As wages and pensions rise, a larger portion of someone’s income can become taxable even if their purchasing power has barely improved.
This is known as fiscal drag. It allows tax receipts to increase without an increase in the headline Income Tax rate.
For example, consider someone whose annual earnings rise from £12,000 to £14,000. With a £12,570 allowance, £1,430 would fall above the threshold. At a 20% rate, that produces £286 of Income Tax, assuming no other income or adjustments.
The person earns more, but part of the increase goes towards tax. Rising living costs may also absorb some of the remaining gain.
How Frozen Thresholds Affect Workers and Pensioners?
Minimum-wage workers can already earn enough to pay Income Tax. Whether they do depends on their annual earnings, hours worked and other taxable income.
A higher hourly wage does not automatically mean every worker owes the same amount. Someone working a few hours each week may remain below the allowance, while a full-time colleague can be well above it.
Pensioners face a similar issue when taxable pension income rises. The relevant figure is their combined taxable income, rather than the State Pension or workplace pension considered separately.
For instance, a pensioner with £16,000 of annual taxable pension income would have £3,430 above the standard allowance.
Under a simple 20% calculation, that means £686 of Income Tax. An £18,000 allowance could remove that liability if all other relevant rules stayed unchanged.
How Much Tax Could You Save Under the Proposal?
The potential saving comes from paying tax on less income. It would not mean receiving the £5,430 allowance increase as a cash payment.
The current Income Tax rates and allowances provide the starting point for the calculations below. They use the 20% basic rate applying to these income levels in England, Wales and Northern Ireland.
Current and Proposed Allowance Comparison
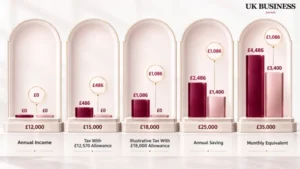
| Annual Income | Tax With £12,570 Allowance | Illustrative Tax With £18,000 Allowance | Annual Saving | Monthly Equivalent |
| £12,000 | £0 | £0 | £0 | £0 |
| £15,000 | £486 | £0 | £486 | £40.50 |
| £18,000 | £1,086 | £0 | £1,086 | £90.50 |
| £25,000 | £2,486 | £1,400 | £1,086 | £90.50 |
| £35,000 | £4,486 | £3,400 | £1,086 | £90.50 |
These are illustrative calculations, not an announced tax package. They assume employment income, a full Personal Allowance, unchanged basic-rate taxation and no other income or reliefs.
They exclude National Insurance, pension deductions, student loan repayments and benefit changes. Monthly figures are annual savings divided by 12.
At £25,000 of income, the calculation would be:
- Current taxable income: £25,000 minus £12,570 equals £12,430
- Proposed taxable income: £25,000 minus £18,000 equals £7,000
- Illustrative saving: £5,430 multiplied by 20% equals £1,086
Who Would Benefit and Who Might Not?
People below the existing allowance: Someone who already owes no Income Tax would generally receive no direct Income Tax saving. An unused allowance is not normally paid out as cash.
People earning between £12,570 and £18,000: Their saving would be limited to the tax they otherwise owe. This explains why the £15,000 example saves less than the £25,000 example.
Self-employed people: The relevant starting point is normally taxable profit, alongside other taxable income, rather than business turnover. Business expenses and applicable reliefs therefore matter.
Higher-income taxpayers: Current rules reduce the allowance by £1 for every £2 of adjusted net income above £100,000. An eventual reform would need to specify how tapering and tax bands would work before reliable savings could be calculated.
Scottish taxpayers: Scotland shares the standard Personal Allowance but has different rates and bands for employment and pension income. The table’s 20% examples should therefore not be treated as Scottish calculations.
Households receiving means-tested benefits: A lower tax bill may affect the income used to calculate benefit entitlement. The tax saving should not automatically be described as an identical increase in overall household income.
What Has the Government Said About the Proposed Increase?
HM Treasury responded on 5 May 2026, saying it had no plans to raise the allowance to £18,000.
It estimated an annual cost exceeding £40 billion and argued that higher earners would benefit more than basic-rate taxpayers on average. Its response also highlighted the implications for public service funding.
The Government’s position is to maintain the threshold through 2030/31, ending on 5 April 2031. That does not establish £18,000 as the allowance from April 2031.
For taxpayers, the distinction matters: a campaign can attract support without creating a new entitlement. Household budgets should continue to use the rules currently in force.
What Happens if the Petition Reaches 100,000 Signatures?
Under the parliamentary petitions process, petitions reaching 100,000 signatures are considered for debate. A debate is not guaranteed, although qualifying petitions are usually debated.
The Petitions Committee may decide against arranging one if the subject has recently been debated or is already scheduled for discussion.
A debate would give MPs an opportunity to discuss the proposal and question the Government. It would not itself amend tax law or instruct employers to change payroll deductions.
Who Can Sign and When Does the Petition Close?
British citizens and UK residents can sign before 30 September 2026.
Readers wishing to support the proposal can open the official petition linked above, select the signing option and follow the form and confirmation instructions.
After the deadline, readers can check the petition page for updates about its outcome. Reaching the deadline does not make the proposed allowance effective.
Conclusion
The HMRC Personal Allowance increase campaign highlights how frozen thresholds can increase tax pressure as incomes rise. An £18,000 allowance could reduce Income Tax for many people, but the benefit would vary.
The worked examples show why some basic-rate taxpayers could save £1,086 annually while others would save less or nothing. For now, the proposed increase remains a campaigning demand, with no approved implementation date.
Frequently Asked Questions
Has the £18,000 Personal Allowance Been Approved?
No. The standard allowance remains £12,570, and the Government has not approved the petition’s proposed increase.
Is HMRC Running the Personal Allowance Campaign?
No. Mike Haynes created the petition through the UK Parliament petitions website.
Would Pensioners Benefit From the Proposed Increase?
Pensioners paying Income Tax could benefit. Those whose taxable income already falls below their allowance may receive no direct tax saving.
Would the Higher Allowance Apply in Scotland?
The standard Personal Allowance applies across the UK. However, Scottish rates and bands mean potential savings can differ.
Would National Insurance Contributions Also Fall?
Not automatically. National Insurance has separate rules, so a Personal Allowance increase alone would not establish a reduction in contributions.
Is There a Confirmed Date for the Allowance to Increase?
There is no confirmed start date for an £18,000 allowance. The petition’s closing date is not an implementation date.
Does a Parliamentary Debate Guarantee a Tax Change?
No. A debate allows parliamentary discussion, but changing the allowance would require a separate policy and legislative process.